
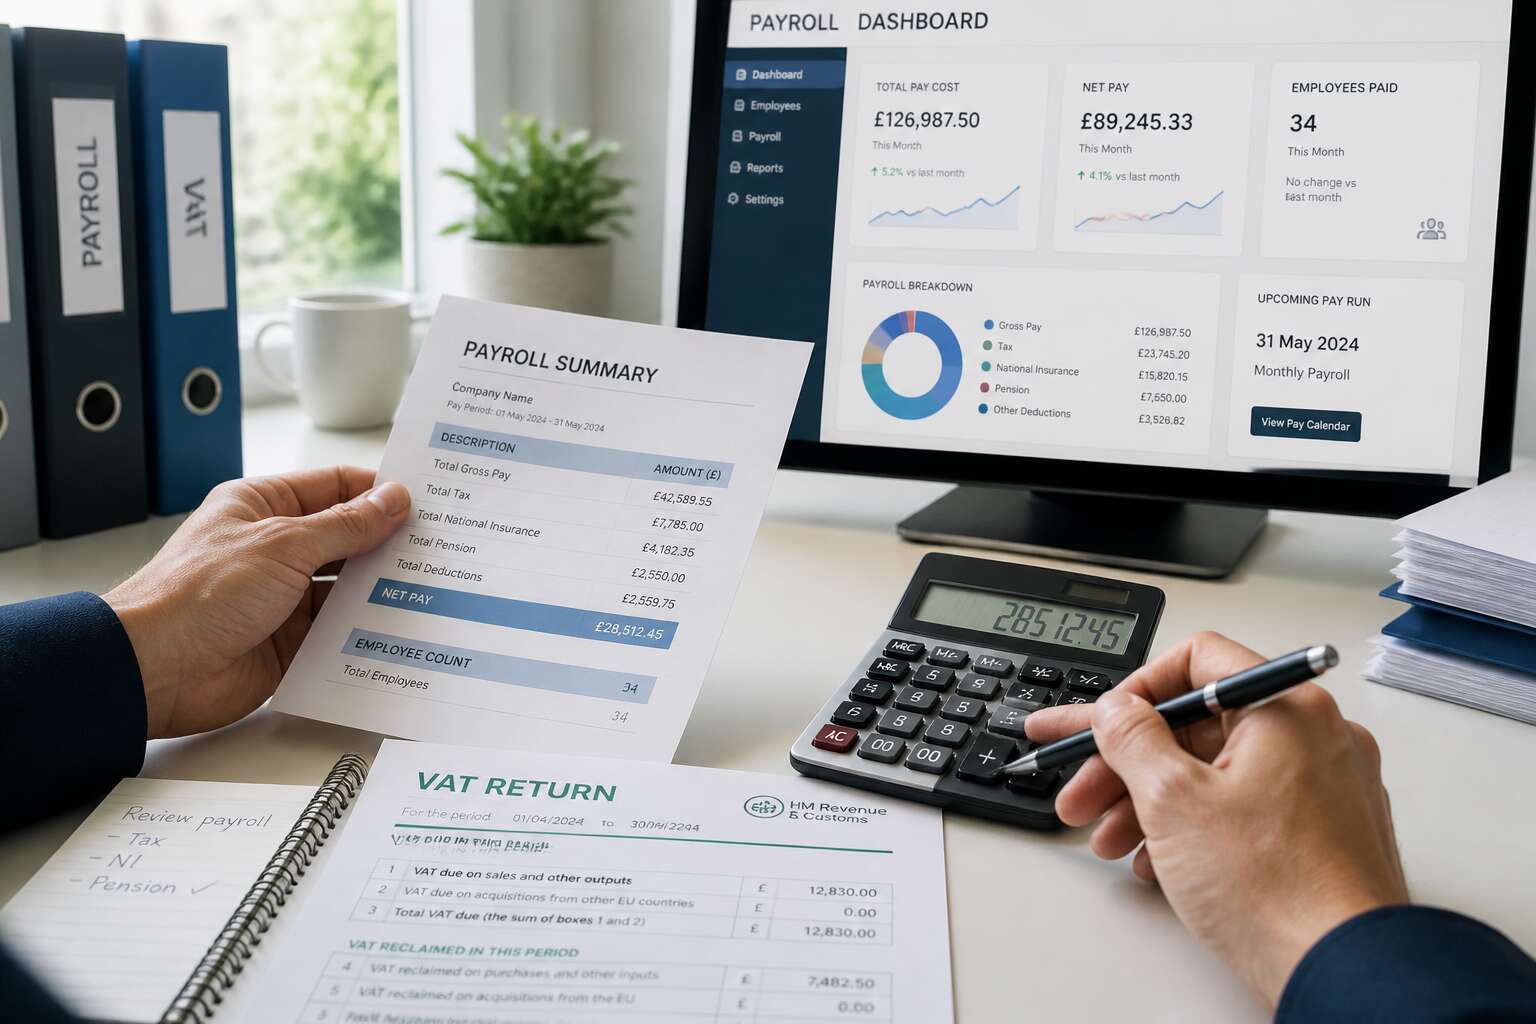
Understanding the Basics of Payroll Outsourcing and Tax
Defining Payroll Services and Their Scope
Outsourcing payroll in South Africa is rarely a neutral administrative decision. It repositions liability, reshapes cash flow, and alters how your payroll services vat obligations are calculated and discharged. A third party processing your wage run does not extinguish your accountability to SARS; it redistributes the operational burden while leaving the statutory risk squarely with you.
The scope of a payroll provider’s mandate typically includes computing remuneration, handling UIF and PAYE deductions, and reconciling employee benefits. However, the VAT treatment of their own fees requires scrutiny. SARS treats payroll services vat as applicable to the provider’s administration charges, not to the gross salaries processed. This distinction affects how you claim input VAT and how contracts should be structured. Understanding this boundary prevents overreach and surprises during verification.
The Role of the Tax Authority in Payroll Processing
SARS does not need an office badge to attend your payroll run. The tax authority’s interest in payroll processing is structural, not ceremonial. Every wage payment triggers obligations that exist independently of who calculates them. PAYE, UIF, and SDL flow to the fiscus through your payroll pipeline.
Outsourcing payroll does not change the equation. The registered employer remains the taxpayer of record. SARS will assess penalties and interest against your entity, not your payroll provider, if deductions arrive late or contain errors. You can delegate the arithmetic, but not the accountability!
SARS expects payroll services vat to be handled with the same precision as the wage calculations. The authority draws a clear line between employee remuneration and provider fees. Only the latter attracts VAT, so your input claim must align with the provider’s invoice, not the salary schedule. Payroll services vat never touches the gross wage bill.
Key Differences Between Direct Employment and Outsourced Payroll
Outsourcing payroll shifts the administrative burden, but the tax risk stays anchored to the employer. SARS treats your payroll service provider as an agent, not the principal. The PAYE, UIF, and SDL obligations remain yours, whether calculated in-house or by a third party. Get the split wrong and the penalties land on your entity!
Direct employment means your finance team handles registrations, returns, and payments. Outsourced payroll introduces a new layer: the service provider’s fee. That fee attracts payroll services vat, which you can claim as input tax if the provider is vat-registered and the invoice complies. The salary amounts themselves sit outside the vat net.
Consider the key differences:
- Liability for late submissions stays with the employer, not the provider.
- The vat treatment applies only to the provider’s fee, never to gross wages.
- Your input claim depends on a proper vat invoice specifying payroll services vat.
Who Is Responsible for VAT Reporting in an Outsourced Model?
The VAT reporting responsibility in an outsourced model follows the money. Your payroll provider accounts for output VAT on their fee. That fee attracts payroll services vat at the standard rate. Your company holds the input claim, but only with a valid VAT invoice. Employee salaries never enter the reporting equation. They are not supplies for VAT purposes.
Here is the practical division:
- The provider submits VAT returns for the service fee.
- Your company verifies the invoice before claiming input tax.
- SARS holds each party accountable for its own reporting.
This separation means your finance team stops preparing returns for wages. The remaining task is the invoice review and the input claim, which is simpler than full VAT reporting.
Common Misconceptions About Payroll and Value Added Tax
The South African Revenue Service treats payroll outsourcing as a taxable service, not a wage transaction. I have seen finance teams stumble on this distinction. Outsourcing payroll does not shift your VAT burden; it changes how you document it. A common error is assuming the provider’s VAT registration covers your entire wage bill. It does not. Payroll services vat applies only to the service fee, never to salaries or employee deductions. Another misconception is that a payslip can substitute for a tax invoice. It cannot! The invoice must show the provider’s VAT number, the fee, and the tax amount separately.
Consider these misunderstandings:
- Employees are not suppliers, so their remuneration carries no output tax.
- UIF and PAYE withholdings are statutory payments, not consideration for a supply.
- Input claims require the provider’s invoice, not your internal payroll records.
Getting these basics right protects your input claim and keeps SARS audits predictable.
Navigating the Technical Rules of VAT on Payroll Fees
Standard-Rated vs. Exempt Supplies in Payroll Administration
The technical rules for payroll services vat force us to confront an uncomfortable truth: the line between standard rated and exempt supplies often depends on interpretation. In payroll administration, a pure processing fee might attract VAT at 15%, while a service that merely facilitates an employment obligation could qualify as exempt.
What determines the distinction? Courts have leaned on the substance of the arrangement. I have found three decisive factors:
- whether the fee is charged for the act of calculation or for the underlying statutory function
- how the contract frames the principal purpose
- whether the output is a report or an actual payment made to an employee
The ambiguity creates real risk. A misclassified supply can lead to under declared output tax or an unexpected liability during a VAT audit. That is why payroll services vat requires more than a cursory glance at the invoice.
Place of Supply Rules for Cross-Border Payroll Services
Understanding cross-border VAT on payroll services requires navigating a layered set of rules that differ significantly from domestic transactions. When a South African company procures payroll administration from an overseas provider, the default position often shifts to the reverse charge mechanism. This means the local business must self-assess VAT, effectively treating the imported service as if it were supplied by a local vendor. The complexity intensifies when considering where the service is actually “used” or “consumed,” as this determines whether the standard rate of 15% applies or if a zero-rated scenario can be justified.
The place of supply rule for B2B services is generally straightforward: the supply is deemed to occur where the recipient is established. However, the application becomes tricky when the provider operates in multiple jurisdictions or when the service involves a mix of automated systems and human intervention. For instance, a foreign entity hosting a cloud-based payroll platform might bundle software licensing with ongoing administrative support. While the software might be treated as an electronic service, the support component could be viewed differently, potentially creating a split in the VAT treatment that requires careful apportionment.
Several critical factors influence how SARS will view these arrangements:
– The physical location of the payroll team performing the calculations
– Whether the service is rendered to a South African branch or the head office abroad
– The existence of a fixed establishment in South Africa that creates a VAT registration obligation
– The contractual terms that specify where the recipient of the service derives the economic benefit
Practical challenges emerge when the invoice from the foreign supplier does not clearly indicate the nature of the service. A lump-sum fee covering both payroll processing and legal compliance advice might inadvertently attract the incorrect VAT treatment. This ambiguity often leads to disputes during an audit, where the burden of proof rests on the taxpayer to demonstrate that the reverse charge was applied correctly. Maintaining robust documentary evidence, including contracts and detailed service descriptions, becomes paramount to substantiate the position taken.
Ultimately, the responsibility for getting this right falls squarely on the shoulders of the South African business. Ignorance of the cross-border provisions does not absolve the liability for under-declared output tax, and penalties can accumulate rapidly. Engaging a tax specialist who understands the nuances of both local legislation and international protocols is not a luxury but a necessity for any organisation dealing with overseas payroll providers. A proactive review of existing arrangements can prevent costly surprises and ensure that payroll services vat is managed with precision and confidence.
Reverse Charge Mechanisms for B2B Payroll Transactions
Navigating VAT on cross-border payroll can feel like decoding a secret language. When a South African business uses a foreign payroll provider, the rules shift, and understanding the reverse charge mechanism is crucial. This essentially moves the responsibility for VAT accounting from the non-resident supplier to the local recipient. You are effectively self-assessing the tax, which can complicate your cash flow projections.
The key lies in the nature of the service provided. Standard B2B payroll services VAT is generally zero-rated if the recipient is a registered vendor in South Africa and the service is imported. However, the South African Revenue Service (SARS) looks closely at whether the service is “directly consumed” in the country.
Several factors influence this determination, including:
– The location of the payroll team managing your account.
– Where the data is processed and stored.
– The contractual terms specifying the place of performance.
Even if the supplier charges you their local VAT, you cannot claim that as input tax. Instead, you must levy the standard 15% output tax on the supply, but you may be able to claim a corresponding input credit. Getting this wrong leads to under-declared VAT, escalating penalties, and unwanted interest. A proactive review of your contract and the physical flow of services ensures your payroll services VAT position remains compliant and defensible.
Handling Input VAT Recovery on Outsourced Payroll Costs
Section 17(1) of the VAT Act permits an input deduction only for tax charged on supplies acquired for the purpose of taxable supplies. That single sentence determines whether your outsourced payroll costs return to you or disappear into the fiscus. The recovery of payroll services vat rests entirely on how convincingly you can trace the administrative work back to your revenue-generating activities.
The difficulty is that payroll serves your employees before it serves your enterprise. SARS has grown skeptical of claims where the link between the payroll function and taxable output feels stretched. Your defence lives in the service level agreement, the workflow records, and the demonstrable fact that payroll accuracy keeps your taxable operations running. Without that documentary thread, the claim fails.
Three conditions must hold before you submit a claim for payroll services vat:
- The supplier must be a registered vendor and issue a compliant tax invoice in your name.
- The service must relate to your taxable supplies, not to exempt or non-taxable activities.
- You must actually pay for the service, with a payment trail that matches the invoice exactly.
Where businesses stumble is on the second condition. A vendor running mixed supplies, part taxable and part exempt, must apportion the input VAT claimed on payroll services vat using a methodology that SARS accepts. That ratio has become a favourite audit target, and an arbitrary percentage will not survive scrutiny.
I have watched a legitimate claim collapse because a single clause in a contract addendum contradicted the original agreement. The documentation burden is relentless. Every invoice, every payment record, every amendment must align. The moment your payroll provider restructures its fees or your vendor status shifts, the recovery position changes, and the evidence must change with it. Input VAT recovery on outsourced payroll costs is a matter of proof, not presumption, and the paper trail you keep today is the only thing standing between a clean claim and an assessment you never saw coming!
The Impact of Partial Exemption on Payroll Bureau Operations
Navigating the technical rules of payroll services VAT can feel like walking a tightrope, especially when your business operations straddle both taxable and exempt supplies. The crux of the matter often lies in the apportionment of input tax credits. SARS does not accept blanket claims or guesswork. They require a method that fairly reflects the extent of taxable use, and for many, the turnover-based formula serves as the standard starting point.
However, this is where the complexity of payroll services VAT truly surfaces. If your company is partially exempt, the standard formula might not be accurate. It is crucial to record the underlying reason for each payroll-related cost. For instance, if your payroll department facilitates the administration of staff who generate exempt income, that portion of the outsourced fee must be separated. You need to demonstrate a direct and clear link between the expense and the taxable income stream.
To strengthen your position, maintain a comprehensive file that documents the rationale behind your specific apportionment ratio. This should include:
– Detailed invoices from your payroll provider that segment services by department or function.
– A written explanation of the business activities that generate exempt income versus taxable income.
– Records showing the actual time or headcount allocation used to calculate the taxable percentage.
Even with these precautions, the practical application of payroll services VAT demands constant vigilance. A change in your business model, such as launching a new financial product that creates exempt income, will immediately impact your recoverable amount. You cannot simply apply last year’s ratio. Proactive adjustments are necessary to avoid interest and penalties. The ultimate goal is accuracy, and achieving that requires a thorough understanding of how every rand spent on payroll services VAT aligns with your taxable enterprise, ensuring you only claim what is rightfully due.
Practical Considerations for Choosing a VAT-Compliant Provider
Evaluating Provider Knowledge of Local VAT Legislation
Selecting a payroll provider in South Africa involves more than comparing monthly fees. The hidden cost of non-compliance often surfaces during a SARS audit, and your provider’s understanding of local VAT legislation becomes your first line of defence. A provider with a seasoned VAT practitioner on staff will review your invoices for accuracy, specifically checking output tax on fees charged and input tax on third-party disbursements.
You should also verify how their software handles the updated VAT rate changes and the specific rules for deemed supplies. The system must archive historical tax periods correctly for future assessments.
To structure your evaluation, ask these targeted questions:
1. How do you determine the VAT treatment for travel and accommodation reimbursements billed to the client?
2. Can you provide a sample VAT reconciliation report from your payroll software?
3. What is your procedure for correcting a VAT error discovered on a previous return?
The right partner will not just process payslips. They will proactively flag transactions with uncertain VAT implications, protecting your business from interest and penalties. Their knowledge directly safeguards your cash flow, turning a routine administrative task into a strategic advantage.
Questions to Ask Your Payroll Bureau About Their Tax Treatment
Behind every clean payslip lies a quiet machinery of compliance, and the choice of who operates that machinery deserves scrutiny far beyond the monthly invoice. When you outsource your payroll, you hand over a piece of your financial narrative, so the questions you ask beforehand should cut to the bone of the provider’s daily reality. You are not searching for a vendor; you are searching for a custodian of your tax integrity.
Elevate the conversation beyond the basics and probe how they treat the gray areas of the law. The answers will reveal whether you are working with a button-pusher or a strategist who understands that payroll services vat obligations change with every legislative cycle. Consider asking them directly how they handle fluctuating circumstances, such as ad-hoc third-party payments or the tax treatment of travel reimbursements that are re-billed to a client.
To structure your evaluation, you might consider a practical checklist:
1. How do you determine the correct treatment for disbursements versus recharges on an invoice?
2. Can you demonstrate how your software manages the input tax claims for these transactions?
3. What is your internal process when a new interpretation is released or a VAT rate is adjusted mid-cycle?
The quality of these answers should give you confidence in their technical depth. A provider who gets this right will not just keep you compliant; they will shield you from the administrative burdens that surface during a SARS audit. Ultimately, the true value of a payroll partner is measured not by the software they use, but by how they connect that software to the complexities of payroll services vat on your behalf.
How to Audit Your Current Payroll Invoice for VAT Accuracy
Practical considerations often separate a compliant payroll operation from one that merely appears sound on paper. I have seen too many finance teams discover discrepancies only after an invoice has been paid and the tax period has closed. That is the worst time to learn about a misinterpretation of payroll services VAT, because the correction process involves multiple parties, revised returns, and a conversation with your provider that nobody enjoys.
An audit of your current payroll invoice should begin with the basics. Check whether the provider charges VAT on the full service fee or if they apply a reduced rate to certain components. Confirm that the invoice separates the supply of staff from the supply of administrative services, because the VAT treatment of each can differ. Most importantly, verify that the VAT number on the invoice matches the one registered with SARS, and that the invoice format meets all the requirements for a valid tax invoice. Discrepancies here will not only cause problems with your input claim, they will weaken your position during any inspection.
You can approach this review methodically.
1. Review the service level agreement and compare it against the line items on your invoice. Any charge for software, reporting, or advice must be clearly identifiable.
2. Examine the underlying payroll data for a sample period. Recalculate the VAT on the gross fees to ensure the provider has applied the correct rate and basis.
3. Scrutinise any third-party costs, such as medical aid contributions or pension fund payments, that appear on the invoice. These are often disbursements and should not carry the same VAT treatment as the provider’s own fees.
4. Confirm that the provider has not charged VAT on amounts that are exempt, such as certain levies or statutory payments collected on behalf of the government.
Applying this scrutiny will reveal whether your vendor understands the distinction between a taxable supply and a mere payment passed through on your behalf. A provider that confuses these categories is likely to make errors elsewhere. That lack of precision becomes your problem, not theirs. The ability to audit an invoice properly is a core skill for anyone responsible for payroll services VAT, because it forces a conversation about the underlying transaction rather than just the final number.
When the review uncovers mistakes, the response of your provider is often more revealing than the mistake itself. A competent partner will acknowledge the error, issue a credit note without hesitation, and explain the procedural change that prevents a recurrence. A weaker provider will offer vague reassurances or blame the software. That difference in behaviour tells you everything about the quality of the compliance culture you have chosen to work with. An invoice is a statement of truth about a transaction, and if that truth is unreliable, you cannot trust the broader relationship either. Regular audits of this nature are not an administrative burden; they are the only effective way to turn a paper trail into genuine peace of mind.
VAT Grouping and Its Effect on Payroll Service Charges
Selecting a provider for payroll services vat compliance often feels like choosing a partner for a long journey. You are not merely buying a calculation. You are entrusting the accuracy of your financial obligations to people whose processes remain invisible to you. The real test emerges when you ask about their internal checks. A provider who hesitates when you question their VAT treatment has already given you the answer you need.
VAT grouping adds another layer of complexity to this decision. When entities within a group structure combine for VAT purposes, the payroll charges between them can lose their taxable status. This changes the flow of your invoices entirely. The supply of staff becomes a transaction between connected parties, and the administrative fee may fall outside the scope of VAT altogether. Your provider must understand whether your structure qualifies for this treatment before they prepare a single payslip, because the effect on your charges is immediate and sustained.
The conversation about grouping should happen before you sign anything. Ask the provider how they handle a scenario where payroll services vat applies to the fee but not to the staff supply. Their answer will reveal whether they have thought through the distinction or simply follow a default setting in their software. A thoughtful response indicates a partner who understands the architecture of your business. A vague response suggests you will be the one explaining these nuances to them later.
Understanding this interplay between group registration and service charges changes how you evaluate cost. A lower headline rate may conceal an inability to apply the correct VAT basis within a group structure. That miscalculation surfaces later as an unexpected adjustment, and you absorb the difference. The relationship between provider and client is tested by such moments. The provider who proactively raises these scenarios demonstrates a depth of knowledge that protects your position long before any invoice lands on your desk.
Avoiding Penalties: Common Compliance Pitfalls in Payroll Billing
The payroll services vat decision demands vigilance. Each invoice carries the risk of potential penalties, and the preparation for compliance is often invisible until the failure appears.
In my practice, I have seen certain pitfalls recur among otherwise diligent bureaus. Consider these:
- Relegating VAT checks to a single individual with no independent review.
- Relying solely on automated systems without periodic manual validation.
- Omitting contractual clauses that define service boundaries for VAT purposes.
These failures do not announce themselves; they appear as an adjustment notice months later. A provider who cannot explain their internal safeguards offers no protection. The compliance requirements for these services reward those who ask for evidence of checks rather than promises of accuracy.
Strategic Implications of VAT on Payroll for Business Growth
Cost-Benefit Analysis of In-House vs. Outsourced Payroll with VAT
Payroll services VAT shapes your margins more than most finance teams expect. The way your provider structures the supply alters your input recovery, your cash flow, and the timing of your expansion. A single output tax error can stall a new contract or a regional hire.
Weighing in-house against outsourcing demands more than comparing monthly invoices. In-house places the weight of software, expertise, and compliance on your shoulders. Outsourcing transfers that burden, yet it adds a VAT line to your operating costs. For many South African businesses, the input recovery on that payroll services VAT charge makes the outsourced route competitive.
- Assess the timing of your input claims
- Review whether disbursements are invoiced separately
- Confirm the place of supply for every cross border fee
Using VAT Reclaims to Offset Payroll Service Expenditure
In South Africa, the question of payroll services VAT often trips up even seasoned financial directors. Many assume that because salaries are exempt from VAT, the entire payroll function slips under the tax radar. That assumption is a costly miscalculation. The reality is that while the salaries themselves are exempt, the service fee charged by a third-party payroll provider is standard-rated at 15%. This distinction forms the crux of compliance for hundreds of businesses outsourcing their payroll.
The confusion stems from a lack of separation between the underlying wage payment and the administration fee. When you process payroll internally, there is no VAT invoice issued for the act of running the numbers. However, when you engage a bureau, you are purchasing a service. That service is subject to VAT, and you must verify that the provider charges you correctly and remits that output tax to SARS. Furthermore, your ability to claim input VAT on that fee depends entirely on your own vendor status and the nature of your supplies.
For businesses operating in the B2B space, the reverse charge mechanism often applies. This shifts the responsibility for VAT accounting from the non-resident supplier to the local recipient. If you use an offshore payroll provider, you cannot simply ignore the missing 15% on your invoice. You are required to self-account for the VAT on that imported service. This process involves declaring the output tax and claiming the input tax simultaneously, provided your company makes taxable supplies. Failure to do so creates a discrepancy that SARS will flag during a payroll services VAT audit.
Another area ripe for error involves the distinction between employees and independent contractors. Payroll services VAT compliance becomes tangled when you pay contractors through your payroll system. Payments to independent contractors for services rendered are not salaries; they are fees for taxable services. If you process these through your payroll bureau, you are effectively using a payment platform that may not cater to VAT on third-party invoices. This often results in a failure to deduct VAT and a subsequent disallowance of the expense deduction.
Businesses frequently overlook the input VAT recovery on ancillary charges bundled into the payroll package. Many providers offer a single all-inclusive fee that covers the software, the processing, and the payslip distribution. They also bundle in “compliance checks” or “UIF submissions.” While the entire fee is subject to VAT, some contracts attempt to apportion portions as non-taxable disbursements. You should carefully review your contract to ensure that any disbursements claimed by your provider are actual payments made on your behalf to third parties, not marked-up internal costs. A genuine disbursement is not subject to VAT, but a recharged service is.
To ensure accuracy in your monthly returns, you should also scrutinize the timing of your input claims. The tax point for a continuous supply of payroll services is often the earlier of the invoice date or the payment date. If your bureau issues invoices on the 25th of the month for a service delivered on the 1st, your VAT period must align correctly. Claiming input VAT in the wrong tax period is a common trigger for interest and penalties. The law requires that you claim the deduction in the period in which the tax point occurs, not when you get around to reconciling the payroll.
Now that the strategic aspects are covered, compliance also relies on proper documentation. Consider these practical checkpoints to solidify your position:
– Verify that your payroll provider’s tax invoice contains all necessary SARS requirements, including their VAT number and a clear description of the services rendered.
– Confirm that the contract clearly distinguishes between the taxable administration fee and any exempt salary payments processed on your behalf.
A final nuance for multinationals involves intermediary holding companies. If your payroll services VAT is charged by a local subsidiary of a global firm, the place of supply is determined by where that subsidiary is established. You cannot claim that the service is supplied from a foreign jurisdiction to avoid VAT. The local entity providing the service is the supplier for VAT purposes. Treating this as an imported service when it is not will lead to incorrect reverse charge calculations and a distorted VAT return. Review your service agreements to identify the actual contracting entity and ensure your accounting treatment matches the legal reality on the ground.
Budgeting for VAT Fluctuations in Multi-Year Outsourcing Contracts
A single percentage point shift in the VAT rate can rearrange an entire year of payroll planning. Decisions around payroll services vat affect business growth in South Africa. When you scale operations, the volume of payroll transactions increases, amplifying the VAT exposure on third party processing fees. A growing workforce means a larger monthly invoice, and the 15% output VAT becomes a recurring line item in cash flow projections.
Multi-year outsourcing contracts present a budgeting challenge. We see providers handle this in two ways. VAT rates can change over a long term agreement, so the contract must address how rate adjustments affect the service fee. Some pass on future VAT increases directly. Others absorb the difference until renewal. Your budget must account for both. Wording on VAT treatment, whether the quoted fee includes payroll services vat, and how the provider handles legislative changes determine the true cost of the contract.
Leveraging Technology to Automate VAT Tracking on Payroll Runs
As your payroll operation expands, the administrative weight of VAT tracking grows with it. Manually reviewing invoices for correct output tax on payroll services vat becomes a source of friction, especially when handling multiple pay runs or employee classifications. The shift from a reactive to a proactive stance requires a fundamental change in how you capture and verify data.
Automation offers a way to remove the guesswork from this compliance process. A purpose-built system calculates the applicable tax rate in real-time, pulling directly from the latest legislative schedule. This eliminates the manual transcription errors that often trigger discrepancies during an audit.
For a growing company, the strategic advantage lies in the data trail itself. An automated solution creates a clear, immutable record of every transaction.
– It flags zero-rated services, like those provided by an independent contractor, instantly.
– It separates exempt supplies from standard-rated fees without human intervention.
– It documents the rationale behind every calculation, providing a clear audit trail.
This shift in approach transforms payroll services vat from a year-end scramble into a continuous, verifiable process. The finance team gains visibility into current liabilities, allowing for accurate cash flow forecasting. Instead of reconciling past mistakes, your business can focus on future growth, secure in the knowledge that every payroll invoice reflects the correct tax obligation. The technology does the heavy lifting, turning a complex regulatory requirement into a structured, reliable part of your financial operations.
Future-Proofing Your Payroll Model Against VAT Rate Changes
Every payroll cycle carries hidden costs that extend far beyond the invoice. When your payroll services VAT handling is reactive, you are not just losing time; you are actively eroding your competitive edge. A single misapplied rate can ripple through your financial statements, undermining the very growth you are trying to fund. For South African businesses, where SARS scrutiny is intense, the strategic implications are immediate. You cannot afford to treat tax as a back-office afterthought.
Future-proofing your payroll model against VAT rate changes requires deliberate architecture. The system you choose today must accommodate tomorrow’s legislative shifts without a complete overhaul. Consider the specific mechanisms that build this resilience:
– Automated rate updates sourced directly from the SARS publication feed
– Geospatial tax determination for employees working across multiple provinces
– Contractual clauses in outsourcing agreements that mandate compliance with new VAT schedules
These elements transform a reactive process into a strategic asset. The payroll services VAT framework becomes a shield against unexpected adjustments, allowing your finance team to forecast accurately. When the next rate change arrives, your operations adjust automatically, keeping your business agile and your cash flow predictable. This is how compliance shifts from a burden to a driver of sustainable growth.
0 Comments