
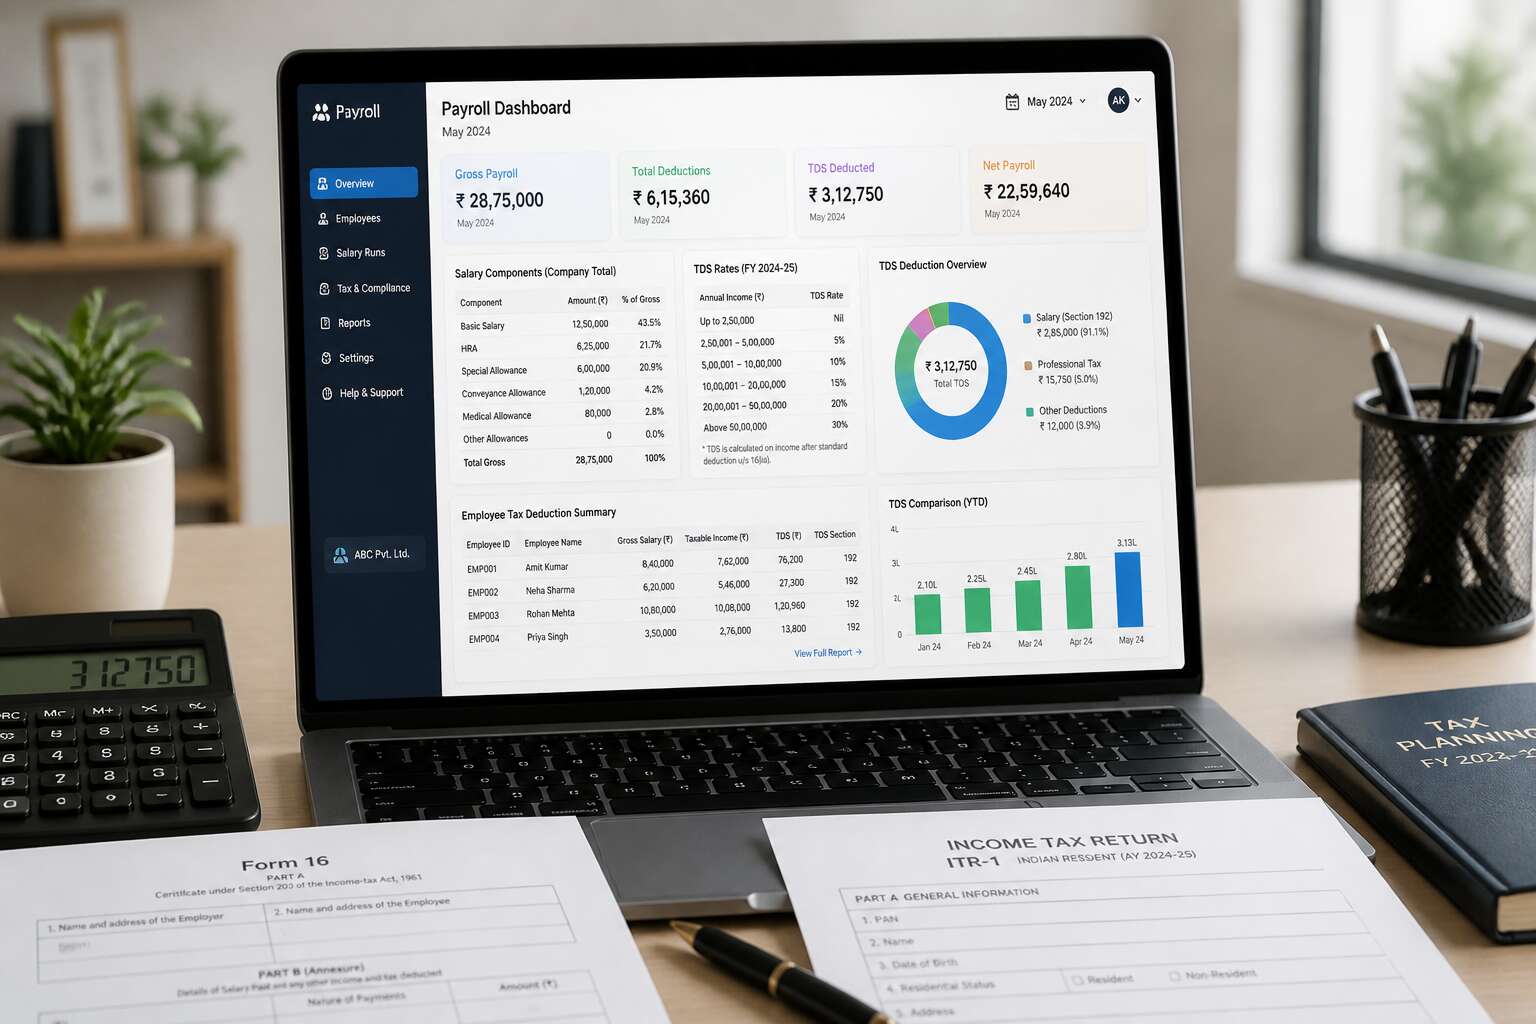
Understanding TDS in Payroll Management
What is TDS and How It Applies to Salaries
Every paycheque in South Africa carries a deduction that employees rarely question. Employers withhold it before salaries hit bank accounts. What we call TDS, or Tax Deducted at Source, drives payroll compliance. The payroll services TDS rate determines precisely how much is taken from each payslip, driven by annual earnings and tax brackets.
SARS expects these figures to match monthly submissions. The rate moves with legislative changes, so payroll systems must stay current. Here is what payroll teams track:
– Gross taxable earnings
– Current tax tables
– Employee tax rebates
Get the rate wrong and you face penalties. Get it right and your payroll runs without friction.
Key Responsibilities of Employers Under TDS Rules
SARS expects precision, yet I have watched too many employers stumble over their monthly obligations. Understanding TDS in payroll management starts with acknowledging that the employer is not merely a middleman. The payroll services TDS rate anchors every calculation before a single rand reaches an employee.
Key responsibilities of employers under TDS rules include:
- Verifying each employee’s tax reference number
- Applying the correct tax tables to gross earnings
- Submitting monthly EMP201 returns without fail
- Issuing accurate IRP5 certificates at year end
These duties demand constant vigilance, especially when legislative changes shift the numbers. A payroll system that lags behind the latest tables creates risk. Employers who treat compliance as routine often discover that SARS rarely forgets a missed payment.
Legal Framework Governing TDS on Payroll
The Income Tax Act, No. 58 of 1962, places unforgiving deadlines on every payroll administrator. This statute, together with the Tax Administration Act, forms the legal framework governing TDS on payroll. Employers who overlook the nuances rarely escape SARS’s attention, and the consequences are never abstract.
Calculating the payroll services tds rate requires applying this framework to each employee’s earnings profile. Deductions for pension contributions, travel allowances, and overtime must align with the Interpretation Notes SARS publishes. In my experience, a rate that looks correct in isolation often fails when the full legislative picture is considered.
- The Fourth Schedule sets deduction timing and payment deadlines
- Secondary legislation covers penalty calculations for late submissions
- Binding rulings clarify ambiguous provisions
The legal framework leaves no room for improvisation. One missed detail echoes across future reconciliations.
Core Factors Influencing TDS Rates
Income Tax Slabs and Their Impact on TDS
India’s taxpayer base recently crossed the 8 crore mark, yet the mechanics of salary deduction remain a mystery to many. The payroll services tds rate is not a single, static number. It is a reflection of the employee’s chosen tax regime and their projected annual earnings.
The income tax slabs are the first determinant. Under the new regime, rates climb from zero to 30 percent as income rises. The old regime offers deductions but demands meticulous record keeping. Your payroll services tds rate calculation must align with the regime the employee selects at the start of the year.
A higher salary naturally pushes an individual into a steeper bracket. This is where the human element enters the equation. An employee earning R1.2 million annually faces a different deduction than a colleague earning R900,000, even if their basic pay is similar. The slab structure creates these boundaries, and the payroll services tds rate follows suit.
Another factor is the surcharge and cess. These add a layer of complexity on top of the base slab rate. For high earners, the effective deduction can be noticeably higher than the stated slab percentage. Your payroll team must apply these additions precisely to avoid under or over deduction.
The choice between regimes also dictates the final liability. Employees often switch mid year, which complicates the payroll services tds rate calculation. Each switch requires a fresh projection of annual income and a recalibration of monthly deductions. It is a delicate balance, one that requires constant attention to the shifting ground of tax law.
Role of Surcharge and Cess in TDS Calculation
The stated slab percentage is only the surface of the deduction. Beneath it, surcharge and cess perform their own quiet calculations. A surcharge applies to individuals crossing specific income thresholds, such as ₹50 lakh or ₹1 crore, while the health and education cess adds a fixed percentage on top of the combined tax and surcharge. These components do not appear in the monthly payslip as separate lines, yet they shape the final payroll services tds rate.
For an employee earning ₹1.2 crore annually, the base 30 percent rate becomes a higher effective burden once the surcharge takes hold. The cess then layers an additional 4 percent onto that elevated figure. The payroll services tds rate therefore reflects a composite figure, not a single statutory number. This is where precision matters. A payroll system that only applies the base slab rate will under deduct, leaving the employee with a sudden liability at year end.
Several elements feed into this calculation:
1. The applicable surcharge percentage based on total income brackets.
2. The 4 percent health and education cess on the tax plus surcharge.
3. The chosen tax regime, which determines the base slab rate.
4. Any rebate under section 87A for lower income earners.
The surcharge and cess are not static. Budget announcements can adjust them, and your payroll services tds rate must track those changes. An outdated table leads to errors that ripple through quarterly returns and annual Form 16s. Employees notice when their net pay shifts unexpectedly, and they will ask questions. Your system needs to explain the numbers with clarity, showing how the surcharge and cess contribute to the total deduction. The rate is a living figure, one that changes with every amendment to the Finance Act. Keeping pace with those amendments is the core of accurate payroll administration.
How Exemptions and Deductions Affect TDS
Finance teams often treat exemptions and deductions as the quiet variables in payroll. They do not change the slab rate on paper, but they alter the taxable income that the rate applies to. An employee who claims a higher deduction under Section 80C or opts for a standard deduction sees their net taxable amount drop below a threshold. The payroll services tds rate then operates on a smaller base, which changes the entire deduction picture.
The intricacies of these adjustments are numerous and often misunderstood:
– Exempt allowances such as HRA, which require documentary proof from the employee.
– Deductions for specific investments that only apply under the old tax regime.
– The standard deduction, a flat relief that does not require receipts or declarations.
– Deductions that the organisation must verify before the monthly payroll cycle runs.
A system that misses these inputs fails to compute the correct tax liability. For a high income earner, a missed deduction means an inflated monthly deduction. For a lower earner, it could mean accidental under deduction and a large bill later. The payroll services tds rate is not a fixed number. It is the outcome of a calculation that begins with gross pay, subtracts eligible amounts, and then applies the slabs. The accuracy of that first subtraction is what separates a compliant payroll from one that generates constant queries.
Annual Budget Changes and TDS Rate Updates
Each February, South Africa’s Budget Speech changes payroll calculations. Tax tables shift, rebates adjust, and the calculation is never quite the same for the next twelve months.
Annual budget changes drive TDS rate updates. Finance teams wait for the revised thresholds, the new medical tax credit amounts, and the adjustments to retirement fund contributions. One line in the budget can alter thousands of payslips.
- Changes to the tax bracket boundaries
- Updates to the primary and secondary rebates
- Revisions to interest or dividend exemptions
The payroll services tds rate responds to these shifts with a recalibrated calculation. Missing an update means overcharging an employee or underpaying SARS, neither of which ends well.
Steps to Calculate TDS on Payroll
Gathering Necessary Employee Information
Nine out of ten TDS errors trace back to incomplete employee files. Every February, the same ritual unfolds as workers misplace their tax certificates and payroll teams chase missing forms. The first step in calculating TDS on payroll, gathering necessary employee information, demands meticulous care! I have seen entire deductions go wrong because someone omitted a medical aid contribution. For a correct payroll services tds rate, you need the full picture: tax numbers, identity details, and declared allowances.
A well-organized collection approach reduces frustrations. Assemble the essentials:
- Tax reference numbers
- IRP5 certificates from previous employers
- Medical scheme contribution certificates
- Retirement fund contribution proof
Each item feeds directly into the tax tables. Without these, the calculation may rely on outdated details.
Determining Gross Salary and Taxable Components
The line between gross salary and taxable income is where most payroll calculations falter. Gross salary is the full sum an employee earns: base pay, housing allowances, travel reimbursements, overtime, and performance bonuses. Fringe benefits like company cars or subsidized loans also sit within this figure. To determine taxable components, you subtract exempt items from that gross total. This step demands precision. Without a clear breakdown, your payroll services tds rate may be applied to the wrong base. I often see employers include non-taxable reimbursements by mistake.
The calculation follows a simple sequence:
- Total all remuneration for the month
- Identify and remove exempt allowances
- Deduct retirement fund contributions
- Apply the applicable TDS rate to the remaining amount
This final figure, the taxable component, is what determines the accurate payroll services tds rate for each employee.
Applying Applicable Deductions Under Section 80C
A single misapplied deduction can shift the payroll services TDS rate by an entire bracket. The path to accuracy begins with gathering all Section 80C investment proofs before the March deadline.
To calculate TDS on payroll, follow this sequence:
- Compute total annual taxable income from all salary components.
- Sum qualifying 80C deductions, including Provident Fund contributions, insurance premiums, and ELSS deposits.
- Cap the total deduction at the legal limit, often ₹1.5 lakh, depending on the applicable rules.
- Subtract that from gross income to arrive at net taxable income.
- Apply the payroll services TDS rate to this net figure for accurate monthly withholding.
Calculating Net Taxable Income and TDS Amount
One wrong assumption about an allowance can skew the payroll services tds rate for a full tax year. Calculating net taxable income requires patience, not guesswork. Each salary component, from travel allowances to retirement fund contributions, must be placed accurately in the annual return.
Once gross income is fixed, subtract all permitted deductions and exemptions to reach the taxable figure.
- Total all gross annual remuneration.
- Subtract exempt income and allowable deductions.
- Apply the annual tax tables to the resulting net figure. This reveals the total annual tax liability.
- Divide that liability by 12 to obtain the monthly withholding amount.
The monthly amount changes when salaries adjust mid-year or when an employee submits updated proof of deductions. Recalculating each time remains the only safe course, because a stale payroll services tds rate triggers a query from SARS.
Using Payslip and Form 16 for Verification
The payroll services tds rate means little if the underlying numbers on an employee’s payslip are plucked out of thin air. Think of the payslip as the daily reality and the annual Form 16 as the polished summary. When these documents have a sour relationship, the South African Revenue Service (SARS) gets a seat at the table, and not the fun kind.
Start by comparing the cumulative tax already deducted on the latest payslip against the tax stated on the Form 16. A mismatch here indicates a problem somewhere in the calculation chain. The verification process requires a specific sequence:
– Check the employee’s tax reference number and personal details on both documents.
– Confirm that gross remuneration on the Form 16 equals the total on the twelfth payslip.
– Recalculate the annual payroll services tds rate using the current tax tables to see if the monthly deductions add up.
One subtle factor is the impact of mid-year salary increases, which often skew the figures. If the payslip tax does not match the annual certificate, run the figures again. A quiet afternoon spent recalculating an old payroll services tds rate is far better than a later request for a recalculated IRP5 with a sniff of annoyance from SARS.
Common Compliance Issues and Solutions
Mistakes in TDS Rate Application and Corrective Actions
Every tax season, dread settles over payroll departments. A single misapplied percentage, buried in a spreadsheet, can unravel an entire year of compliance. Mistakes in TDS rate application rarely announce themselves. They emerge months later during audits, as penalties and interest.
Common errors include:
– applying the wrong rate for employees under 65
– using marginal rates instead of annualised income
– overlooking termination payments and their specific thresholds
Corrective action begins with a full reconciliation of every payslip against current tables. Adjustments must flow through the next payroll cycle, with interest charged on late payments. The payroll services TDS rate must be checked monthly against updated SARS publications. The payroll services TDS rate shifts with each circular, and vigilance is the only defence.
Handling Employee PAN and TDS Declaration Errors
Every declaration error is a confession of inattention. A single PAN digit out of place can taint an entire payroll cycle, and the payroll services tds rate becomes secondary to the chaos of correction. Employees often submit expired declarations, or their names diverge from official records, creating silent discrepancies that surface only at year end.
- Verify PAN structure and ownership against the system
- Cross check TDS declarations with payslip inputs
Solutions demand a ritual of vigilance. Reconcile each declaration before processing, and flag mismatches immediately. When errors slip through, recover the difference through the next cycle without drama. The payroll services tds rate remains steady, but human error is the variable we must master.
Penalties for Late TDS Deposit and Filing
In South Africa, a single late TDS deposit can trigger a series of financial penalties. SARS charges 10% per month on unpaid amounts, with interest compounding daily. Employers who overlook filing deadlines face fines that escalate with each passing month. The administrative burden is substantial, yet many payroll teams only discover the costs when penalty notices arrive.
- Late TDS deposit: 10% monthly penalty, capped at 100%.
- Late return filing: R250 to R16,000 per month, based on turnover.
- Underpayment from errors: daily interest plus potential criminal liability.
These charges accumulate over time. The payroll services tds rate is fixed for the year, but the penalties for non-compliance are not. Payroll departments need to embed deadline tracking into their processes. One missed date can easily undo months of careful calculation.
Best Practices for Streamlining TDS in Payroll
Automating TDS Calculations with Payroll Software
Automating TDS calculations removes the guesswork from monthly payroll. When your payroll software applies the latest payroll services tds rate directly from the tax tables, you reduce manual errors and speed up reconciliation. Your team can focus on exceptions instead of rechecking arithmetic.
- Validate PAN and tax declarations before the first pay run.
- Schedule a mid-year review of employee deductions to catch life changes.
- Keep salary structure stable unless regulations force a revision.
Consistency matters as much as accuracy. Each pay cycle should recalculate liability using the same payroll services tds rate logic, which gives you a clean audit trail. This makes annual tax certificates and reconciliations simpler, and it removes the last minute pressure that surrounds tax season. You need a provider that updates its systems when thresholds shift, so your calculations never fall behind the law.
Regularly Updating TDS Rates and Tax Slabs
Tax tables change every year. Occasionally they change twice, which is the revenue authority’s idea of a practical joke. Employers who treat the payroll services tds rate update as a once-off ritual often discover mid-year that an amendment slipped through. Nobody enjoys retroactive payroll adjustments. A sensible rhythm involves one focused session:
- Check the gazette for published rate changes
- Update your payroll system’s rate tables
- Run sample calculations across different salary bands
The goal is parity between your payroll services tds rate logic and the current legal position. When those two disagree, payslips become unreliable. Reconciliation turns into a hunt through old files to establish when divergence started. Consistency in every pay cycle prevents that hunt. Your audit trail stays intact, and tax season loses its drama.
Ensuring Accurate Employee Data Management
Employee data degrades when left unchecked. A mistyped tax reference number or an old residential address nudges the deduction off course. Each stale field creates errors that surface during monthly reconciliations.
Strong data management requires comparing every record against original documents. Revisit those records whenever an employee marries, relocates, or takes on secondary income. The payroll services tds rate remains stable, but the employee’s circumstances do not.
- Validate ID numbers before the first payslip
- Confirm tax residency status each year
- Keep an approval trail for banking detail changes
Accurate employee records keep deductions honest and year-end balancing straightforward.
Synchronizing TDS with Statutory Compliance Calendars
A missed SARS deadline costs more than a fine; it unravels the entire payroll cycle. When the payroll services tds rate calculation shifts, the due dates for declarations and deposits rarely move. This mismatch creates tension. A payroll run completed on the 25th leaves no room for reconciliation if the statutory submission lands on the 1st.
I have seen payroll teams ignore the statutory schedule until the final hour. That approach fails. The workflow follows its own sequence:
- Salary data is extracted at month end.
- TDS rates are validated against the latest SARS tables.
- The EMP201 is filed before the deadline.
- The payment is reconciled with the payroll register.
Each step depends on the previous one. The payroll services tds rate may change annually, but the calendar anchors the entire process. Synchronizing these elements keeps the monthly cycle intact.
Providing Clear TDS Information to Employees
Payroll teams often treat TDS as a confidential calculation, yet employees experience the result as a deduction from their hard earned wages. Providing clear TDS information to employees means showing every step: how gross salary leads to taxable income, and how the payroll services tds rate transforms that figure into a monthly withholding. When an employee understands the sequence, calls to the finance desk drop sharply.
Prepare a simple breakdown with each payslip:
- The taxable salary after exemptions and Section 80C deductions.
- The exact payroll services tds rate applied, referenced against the current SARS tables.
- The cumulative TDS withheld for the tax year.
Employees who see the full picture can verify their own figures before filing returns. That clarity builds trust in the payroll process and reduces corrections.
Outsourcing Payroll to Manage TDS Complexity
Outsourcing payroll shifts TDS complexity to specialists who track every rate change. A competent provider applies the correct payroll services tds rate from the current SARS tables, reducing errors from internal guesswork. The handover demands precise documents and defined deadlines.
The best practice is to verify the provider owns the liability, not merely the calculation. Ask about their data security and audit trail. Consider these steps:
- Define service level agreements for error resolution.
- Review their monthly reconciliation reports.
- Maintain a single point of contact for SARS queries.
When payroll is outsourced, TDS becomes a managed routine rather than a persistent problem.
0 Comments